pdp youtube by icon8 facebook by icon8 Instagram by icon8

保單捐贈旨在透過各類型公眾教育活動,從保險業界及公眾層面,與慈善機構共同宣揚「讓社會成為我們的保單受益人」,鼓勵香港保單持有人,透過更改保單受益人申請,自願捐出不少於百分之一的人壽保障額予心儀的慈善機構,集腋成裘,展現對社會的大愛。
Policy Donation aims at promoting the culture of life insurance policy donation through various public educational activities. From insurance sector, general public to charities, our advocacy drives policyholder to designate society as the insurance beneficairy by changing beneficiary's information. Every donation adds up, as small as 1% sum insured under his/her life insurance policy(s) to charity, will be extended to our community with great love.

保單持有人只要擁有根據《保險公司條例》(香港法例第41章)所簽訂擁有身故賠償成份的保單合約包括:人壽、危疾、住院醫療、殘疾或年金,均可於保單生效期間,透過向保險公司申請保單受益人更改,自願捐出不少於百分之一的人壽保障額予心儀的慈善機構,即已參與保單捐贈。
Any potential donor with an existing life insurance policy complied with the Insurance Companies Ordinance (Chapter 41) of the Laws of Hong Kong is eligible to participate in Policy Donation. Various types of insurance policy, include life insurance, criticial illness, disability income, retirement annunity, are suitable for donation.

我們的目標是讓保單持有人,透過保單捐贈,將關愛社會精神傳承保單受益人。但我們不能否定,有關改動會對原有保單受益人將可獲得的保額比例造成輕微影響。因此,我們建議有關保單捐贈額以1%-5%為限,積少成多。
Our goal is to cultivate policyholder with a caring spirit to the society we live, in which we hope it will be inherited from one generation to the next. However, we cannot deny that the change(s) will bring a slight impact on the proportional of benefit which has been allocated to the original of policy beneficiary. Therefore, we strongly suggest that the charitable donations should be limited to 1%-5%. #Every1counts.

保單持有人可按照個人意願選擇心儀的慈善團體成為保單受益人。與此同時,我們強烈建議捐贈前,可先了解慈善機構的背景、宗旨、服務範圍、捐款用途(可參閱有關的核數師報告), 以及慈善機構近期及未來服務規劃是否能持續滿足社會需要, 都是保單持有人在決定捐贈前對在決定捐贈需要考慮的因素。
Policyholder can choose his/her favorite charity as beneficiary(s) of own free will. We strongly recommend that, before the decision of policy donation is made. policyholder should have a clear understanding about the charity’s background, scope of services, how donation are used (refers to the relevant auditor’s report) in additional to the future planning of the charity in 5 - 10 years.

一般而言,根據香港法例第112章《稅務條例》第88條,屬公共性質的慈善機構或信託團體,均可以公司名義成為保單指定受益人。但必須留意,在保單受益人欄所填寫慈善機構名稱,務必與香港法例第32章/第622章《公司條例》公司名稱及公司註冊編號完全相同,有關受益人更改才能正式生效。
We advocate policyholder(s) to donate 1% sum insured to any charitable institution or trust of a public character under section 88 of the Inland Revenue Ordinance (Cap 112). However, from the operational perspective of insurance companies, any company with the business name   CI number under Companies Ordinance (Cap 32/Cap 622), either it is a for-profit or non-profit making company, is eligible to be designted beneficiary(s). Therefore, company registry   CI number of the charity is a MUST for the procedure to change of beneficiary(s) or to make the claim(s) of death benefit.

若保單持有人經審慎考慮後決定改變原有安排,例如:取消捐贈,或更改受益慈善機構等,可透過再次填寫保險公司的保單更改資料表格,向保險公司正式申請。相關資料的更改次數和百分比並沒有限制,以確保有關保額分配為保單持有人現存的意願。
If the policyholder decides to change the original arrangement after careful consideration, such as canceling the donation or changing the beneficiary to another charity. He/she can go through the procedure by filling in the “Request of Policy Change Information Form” again. There is no limit to the number of change of beneficiary's information to be made. This is to ensure that the relevant insurance coverage allocated is staying up to date the current wish of the policyholder.

不是。任何生效中的保險合約,只須含有人壽保障成份,均可透過更改受益人作保單捐贈 。
No. Any insurance policy offers a death benefit for the beneficiary is eligible for donation by changing of beneficiary designation.

可保利益存在於保險契約之初,保額正式生效後,保單持有人可不受限制地更改受益人及百份比分配。
然而,部份保險公司考慮有關身故索償手續的需要,對於更改受益人為慈善機構,最高只接受99%保障額作慈善捐贈,以便保留1%予自然人辦理索續手續。 若保單持有人將全數人壽保險捐贈予慈善機構,保險公司將只接受由慈善機構的主要職務負責人提出賠償,並需提交正式授權書。
“Insurable Interest” only exists in time of the insurance contract established. After the insured coverage is officially effective, policyholder can change the beneficiary information as his/her wish without restriction.
However, in considering the ease of death claims application procedure, insurance company(s) tends to approve 99% as the maximium amount of donation to charity, so as to reserve a natural person to be responsible to make claim(s). For the 100% donated policy, only the person in-charge with a proof of authorization is allowed to make the claim on behalf of the charity.

保險公司都已建立更改保單受益人恆常的運作機制,協助客戶(準保單捐贈人)因應不同情況作出受益人資料更改。一般而言,保單持有人只要在保單受益人一欄所填寫慈善機構名稱及註冊編號即可。手續簡單合法,融入生活。
For most of the Insurance companies, they have a well established operating mechanism for the change of policy beneficiary under different circumstance. Generally speaking, policyholder can simply make the change by filling the beneficiary information with company registry   number of the charity. The simple process is legal, integrates into normal life.

為了方便客人捐贈保單,我們特別設計保單捐贈三部曲,協助保單持有人及保險從業員,輕鬆完成保單捐贈。
保單捐贈的主要包括三個步驟 :
  1. 第一步 : 挑選心儀慈善機構
  2. 第二步 : 申請更改保單受益人
  3. 第三步 : 遞交保單捐贈意願書
In order to make the act of donation easy, a trilogy of policy donation is specially designed for both policyholder and insurance practitioner who wish to donate.
It consists of three major steps :
  1. Search for Wishful Charity(s)
  2. Find the Request of Change of Beneficiary Forms
  3. Submit Policy Donation Pledge Form

保單捐贈意願書是一份須由保單持有人親簽的文件,表達保單捐贈的意願,但並不具法律效力。資料經內部處理後,主要用作下兩大用途。
  1. 製作保單捐贈統計予公眾及慈善機構參考,共同推動保單捐贈文化。
  2. 表揚出心出力的保險從業人員,推廣保單捐贈不遺餘力。
Policy Donation Pledge is a non-legal binding document to be submitted by policyholder who intends to record his/her wish to donate policy(s) after death. After the content is anonymized, it serves for two major purposes.
  1. To develop "Annual Statistics of Policy Donation" as a reference for both public   third sector.
  2. To recognize insurance intermediaries who have given his/her best to promote policy donation, thus cultivating our socieity with a caring culture.

不是。遞交保單捐贈意願書屬自願性質,不具法律約束。 保單持有人有權自行決定隨時要求更改或取消已遞交的保單捐贈意願書。
No, it’s not. Submission of a Policy Donation Pledge Form is entirely voluntary. It is neither a contract, nor it is legally binding. The policyholder always has the right to request to amend or cancel the Policy Donation Pledge Form at any time on his/her own decision.

保單受益人屬保單持有人的個人私隱。因此,除非由保單持有人主動通知慈善機構,或透過保單捐贈意願書同意披露相關範圍資料,否則一般情況,慈善機構未必知道自己已成為保單受益人,與一般受益人情况相同。
The designation of beneficiary is the privacy of policyholder. Unless the details is disclosed by the policyholder or the disclosure of fully anonymised personal data based on the consent signed on policy donation pledge by policyholder, charity would NOT be infomed as a beneficiary upon the change. The term   condition is applied to all beneficiary(s).

若保單持有人不幸身故,在死因不存疑點的情况下,保險公司會隨即按正常理賠程序,向各受益人作出賠償。若出現任何指定受益人爭議,通常會由雙方代表律師以調解方式解決。
現實情况,當保單持有人決定作出保單捐贈時,我們不建議保單持有人將相關保單立入遺囑,避免受益人爭議。
Under normal circumstance, a claim without further investigation of the cause of death, beneficiary(s) will recieve the payout from insurance company. In case of dispute regarding to the conflict between beneficiary designation, insurance company would wait until the settlement is reached.
In the most practical way, policyholder who wishes to make policy donation is NOT recommended to designate the beneficiary as "own estate" so to reduce the risk of complication upon death.

更改受益人申請獲正式批核後,慈善機構成為保單受益人安排隨即正式生效。人壽保險受益人的安排具有法律效力,只要有死亡證及備妥文件,保險公司一般30天內便可以發放保險金予受益人,包括慈善機構。
The arrangement of beneficiary designation is a legally binded contractual agreement. The change of beneficiary is made effective immediately once it is approved. Any beneficiary, includes the charity, is eligble to make claim(s) to insurance company with all the require supporting documentation. The process usually takes 30 days before the benefit is paid.

不需要。在香港,購買新的人壽保單之時,受保人與受益人兩者之間,必須要存有「可保利益」的法律關係,以規避道德風險。保單捐贈人與慈善機構之間,並不屬此限。
保單合約正式生效之後,受保人或保單持有人可因應個人意願和需要,透過更改受益人,重新分配保額。保額捐贈亦主要是透過更改現有生效中保單合約,將其中1%受益人份額贈予慈善機構,從而達至捐贈的目的。
No neccessary. In Hong Kong, when purchasing a new life insurance policy, there must be a legal relationship between the insured and the beneficiary with "insurable interest" in existence, so as to avoid moral hazard. The relationshhip between donor and charity does not belong to this case.
Upon insurance contract is officially effective, the insured or the policyholder can redistribute the insured amount by changing the beneficiary according to personal wishes and needs. Our advocacy of Policy Donation shares the same view through changing 1% sum insured of existing life insurance to charity, so as to achieve the purpose of donation.
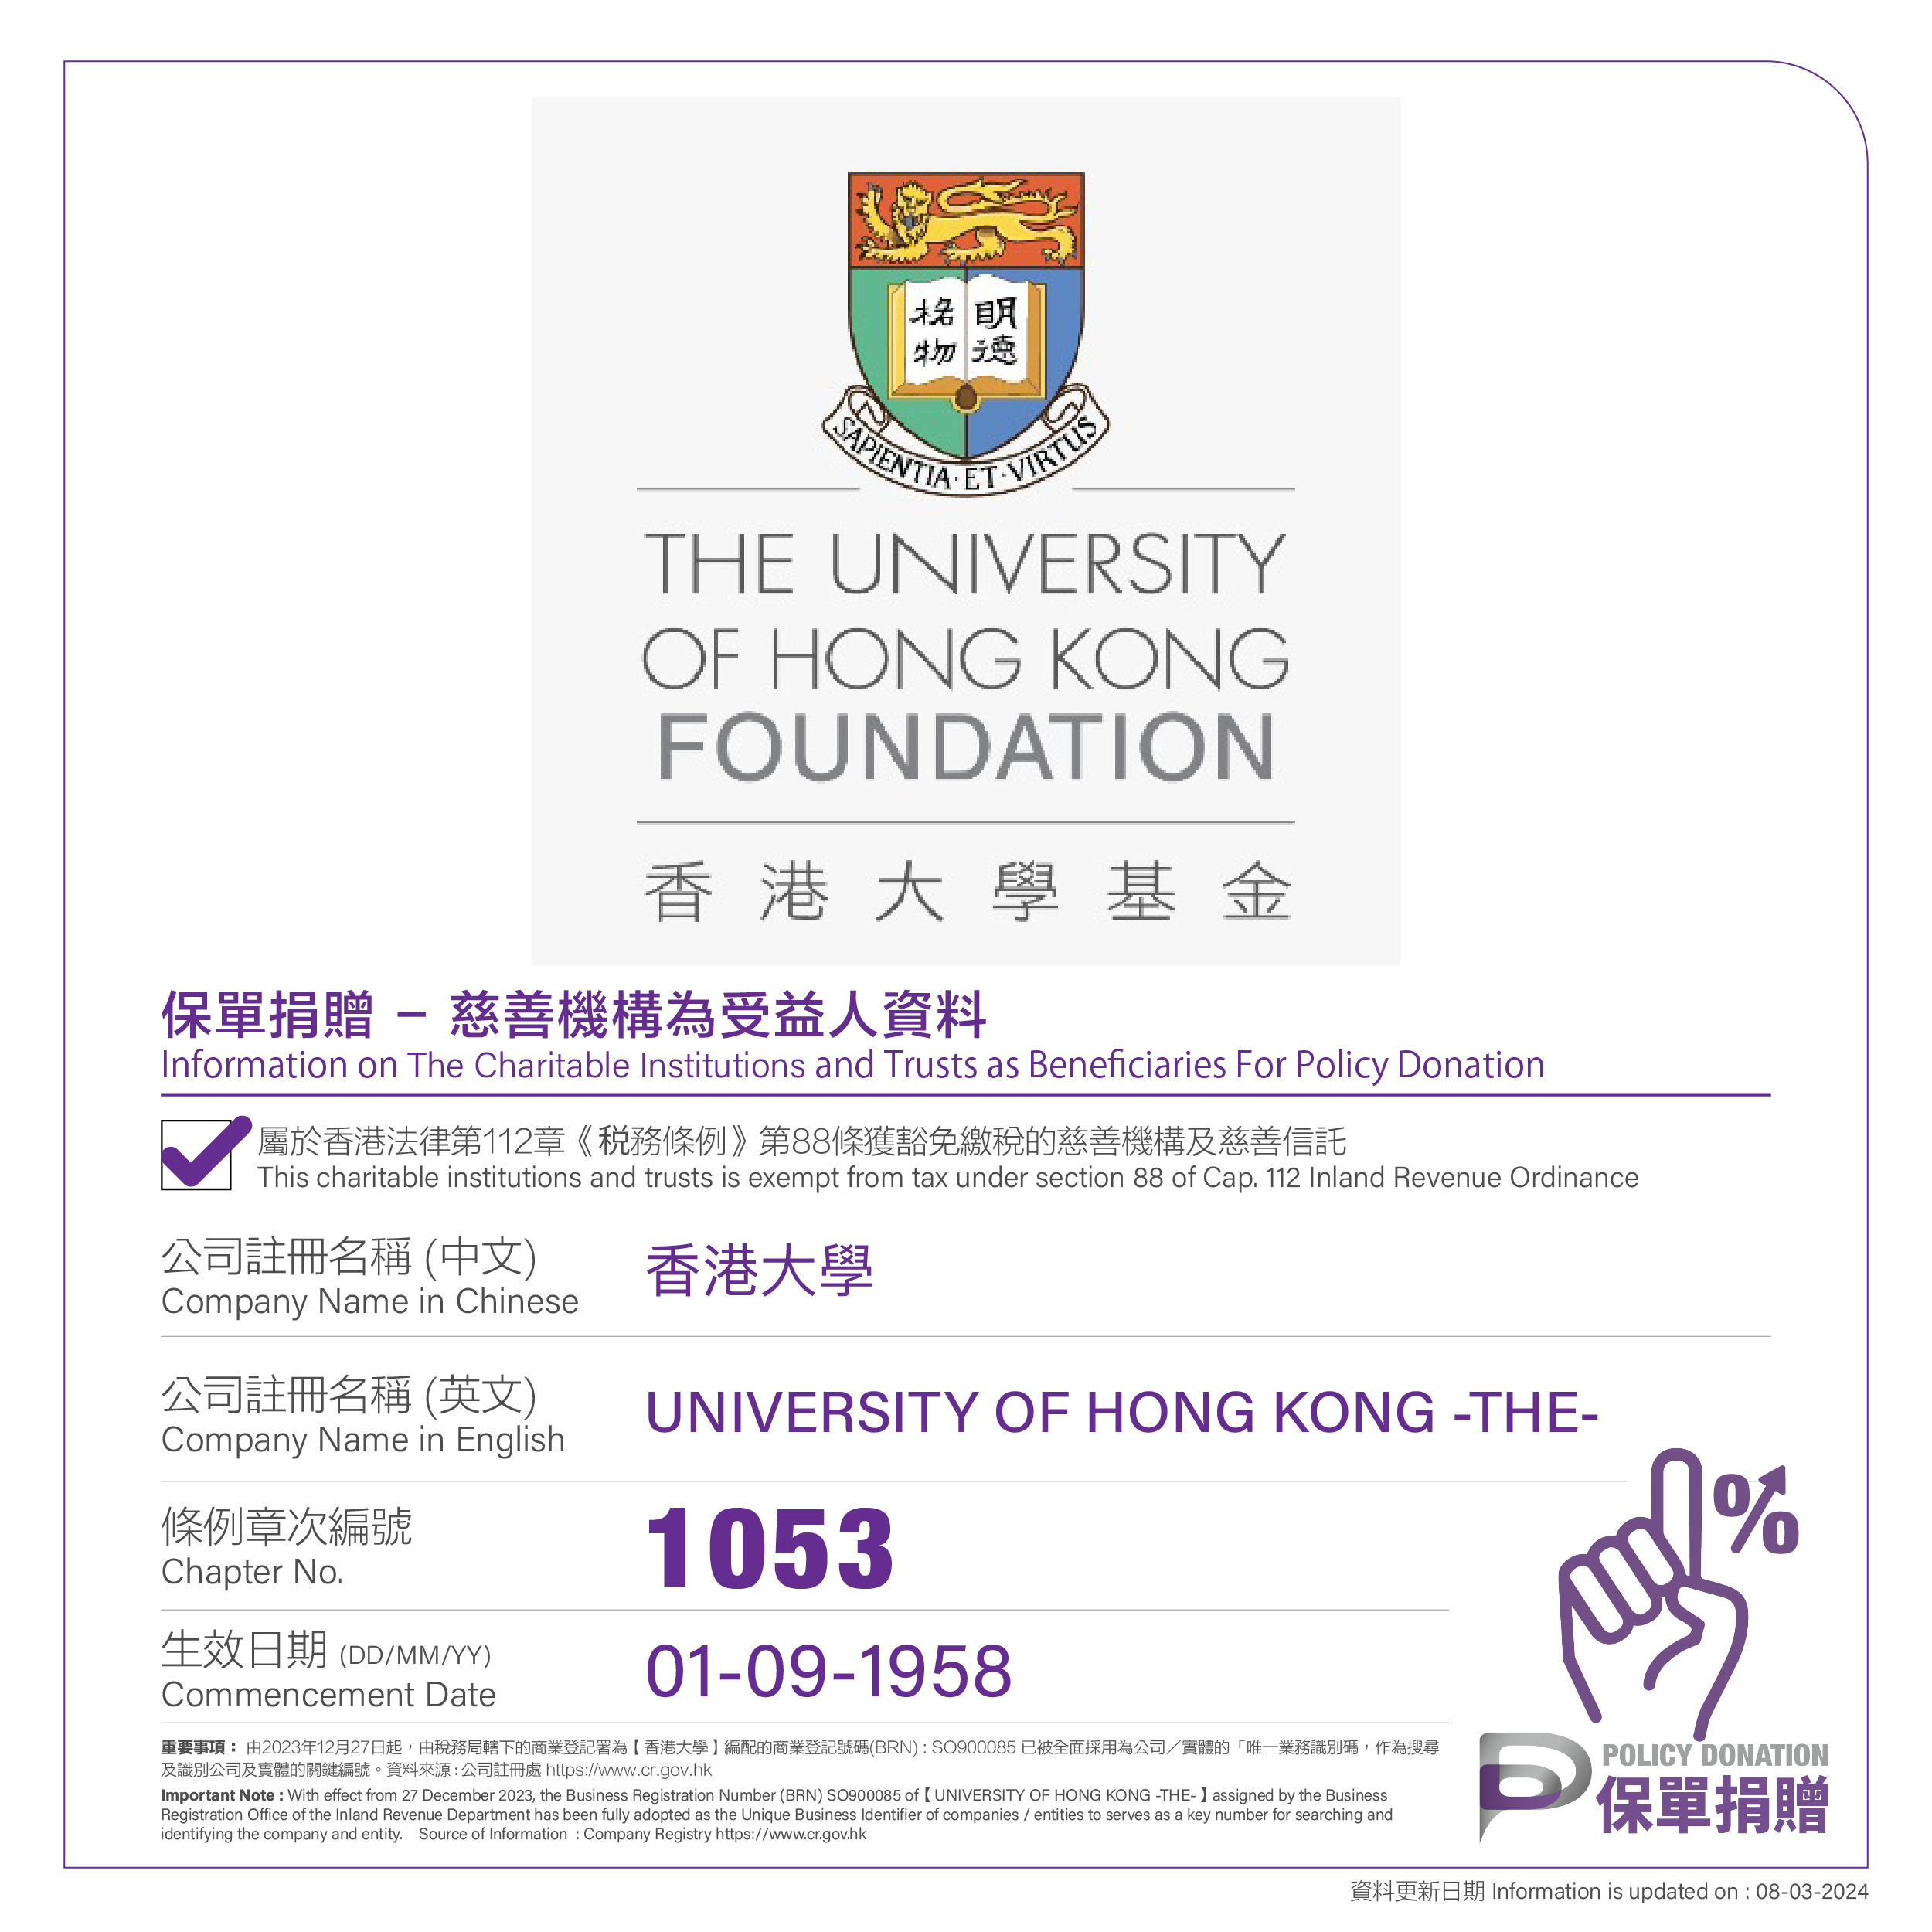
UNIVERSITY OF HONG KONG
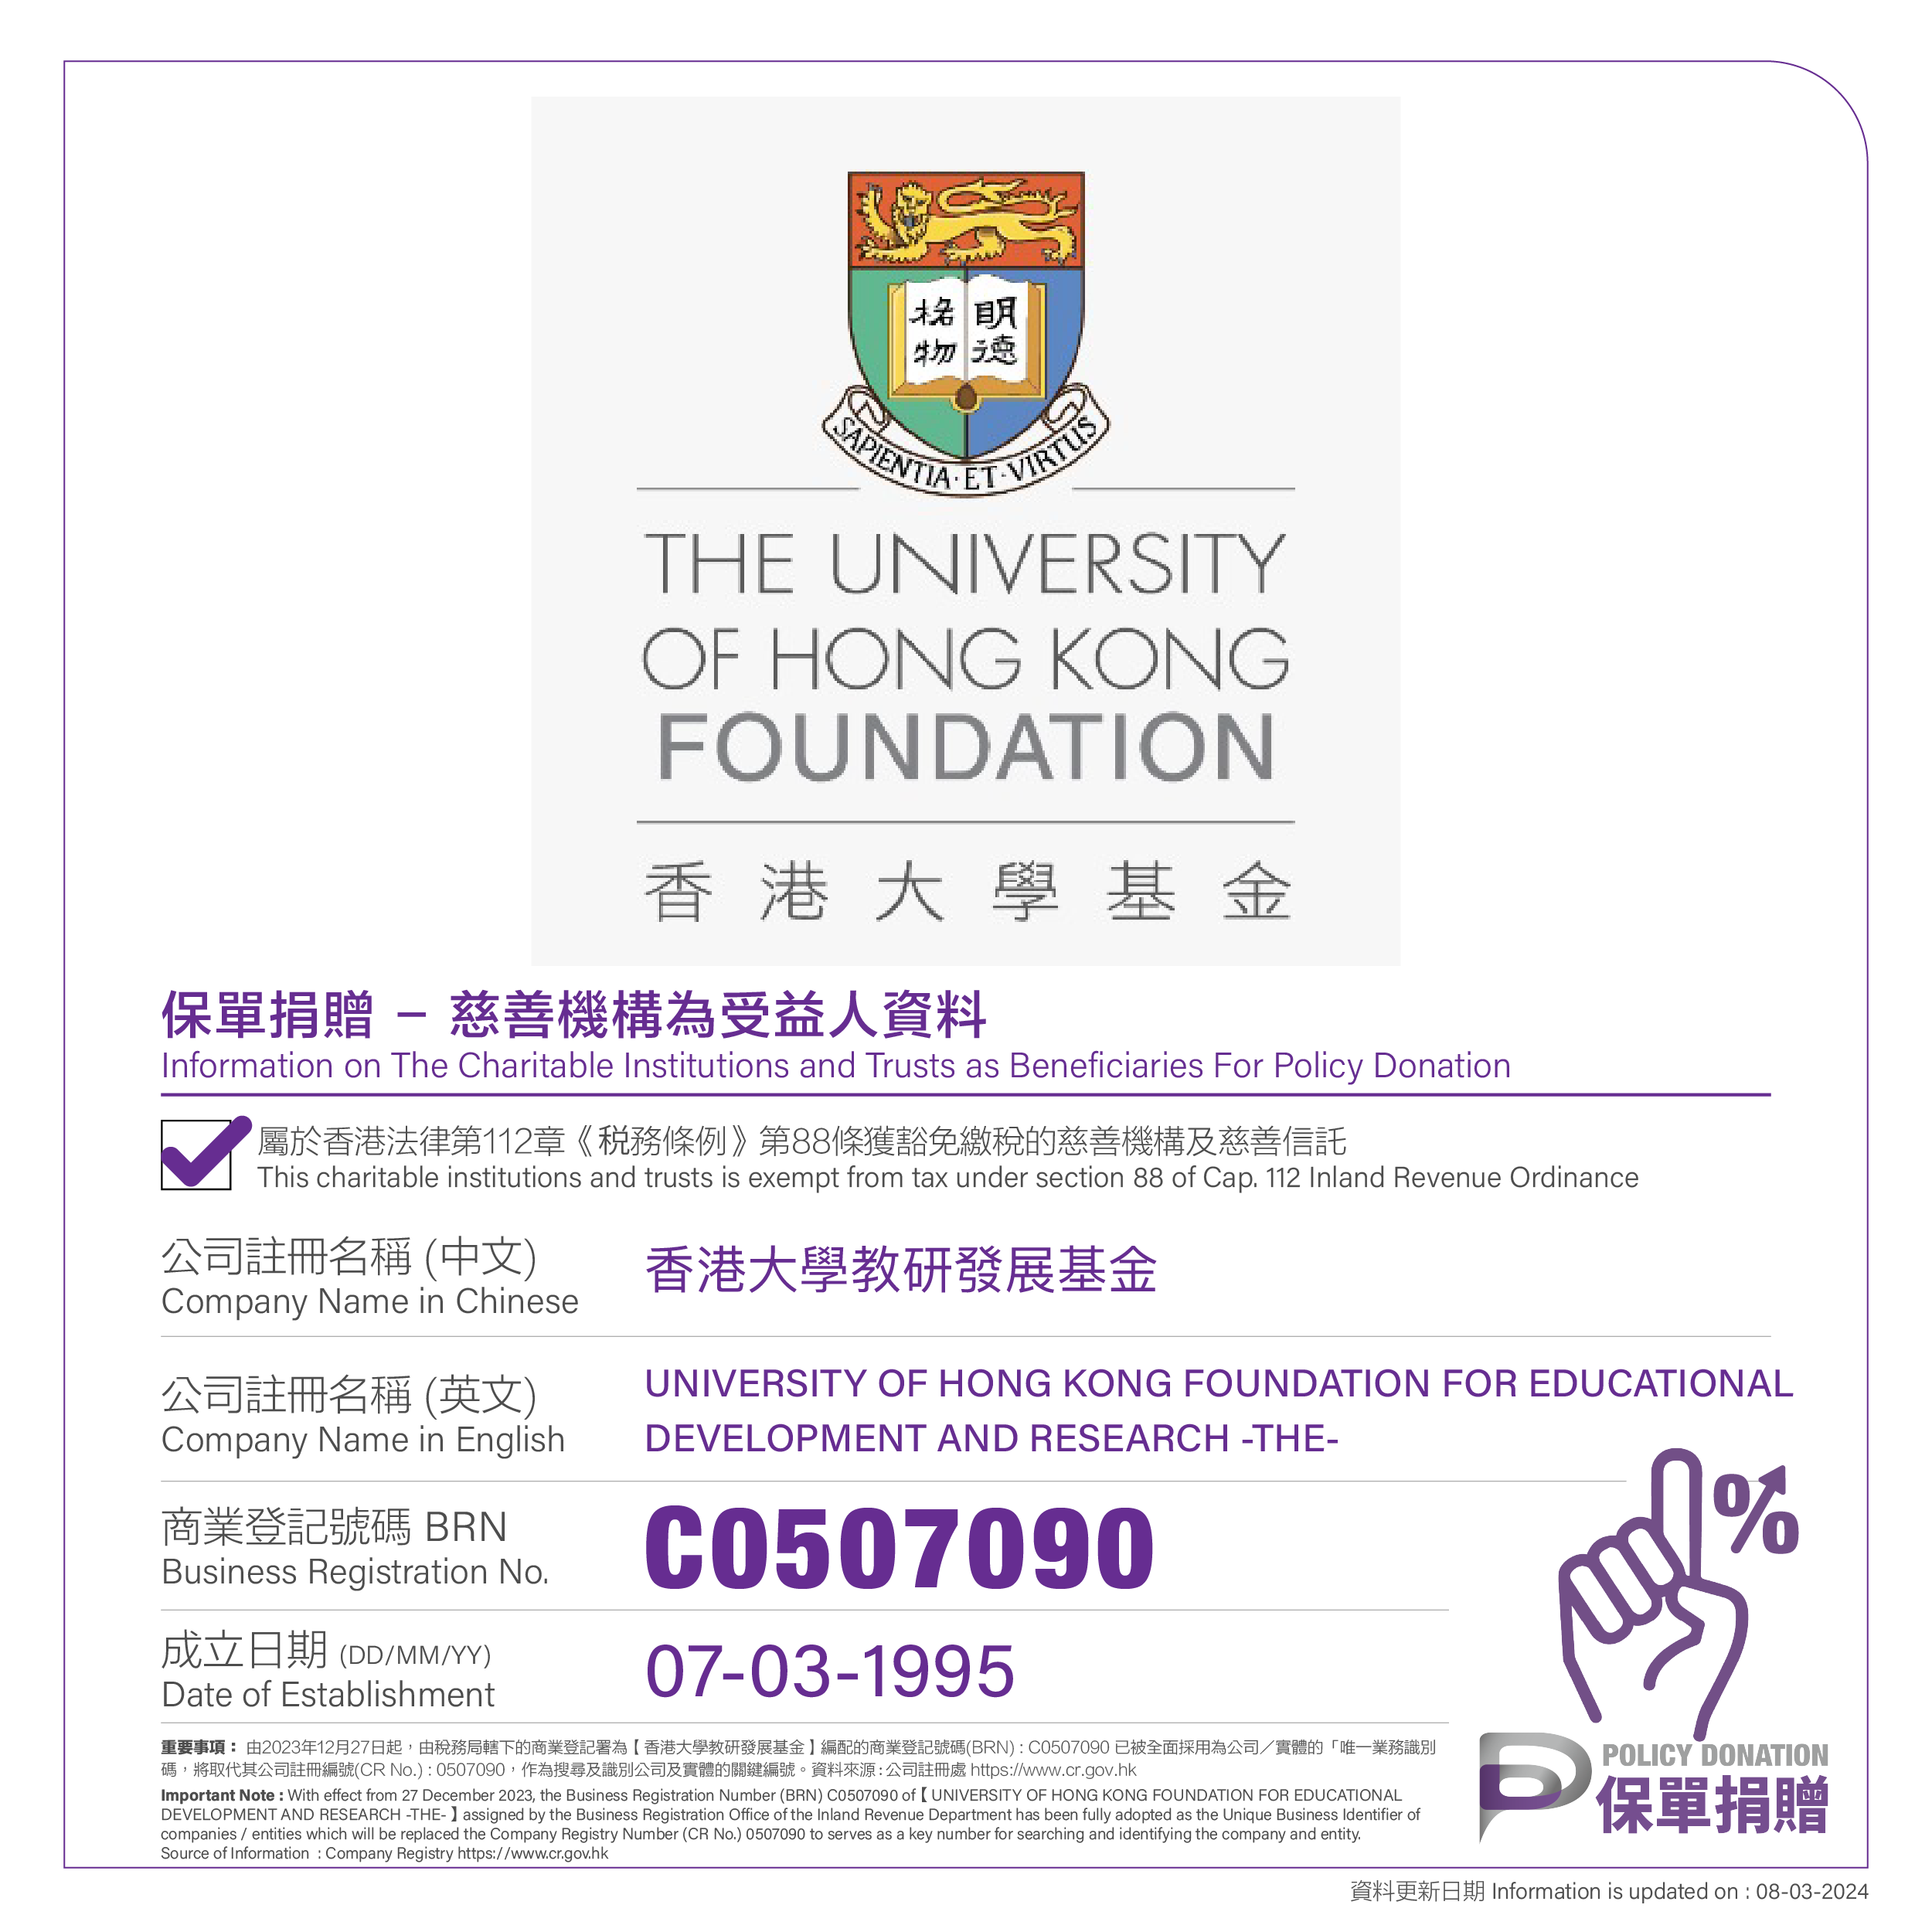
UNIVERSITY OF HONG KONG FOUNDATION FOR EDUCATIONAL DEVELOPMENT AND RESEARCH -THE-
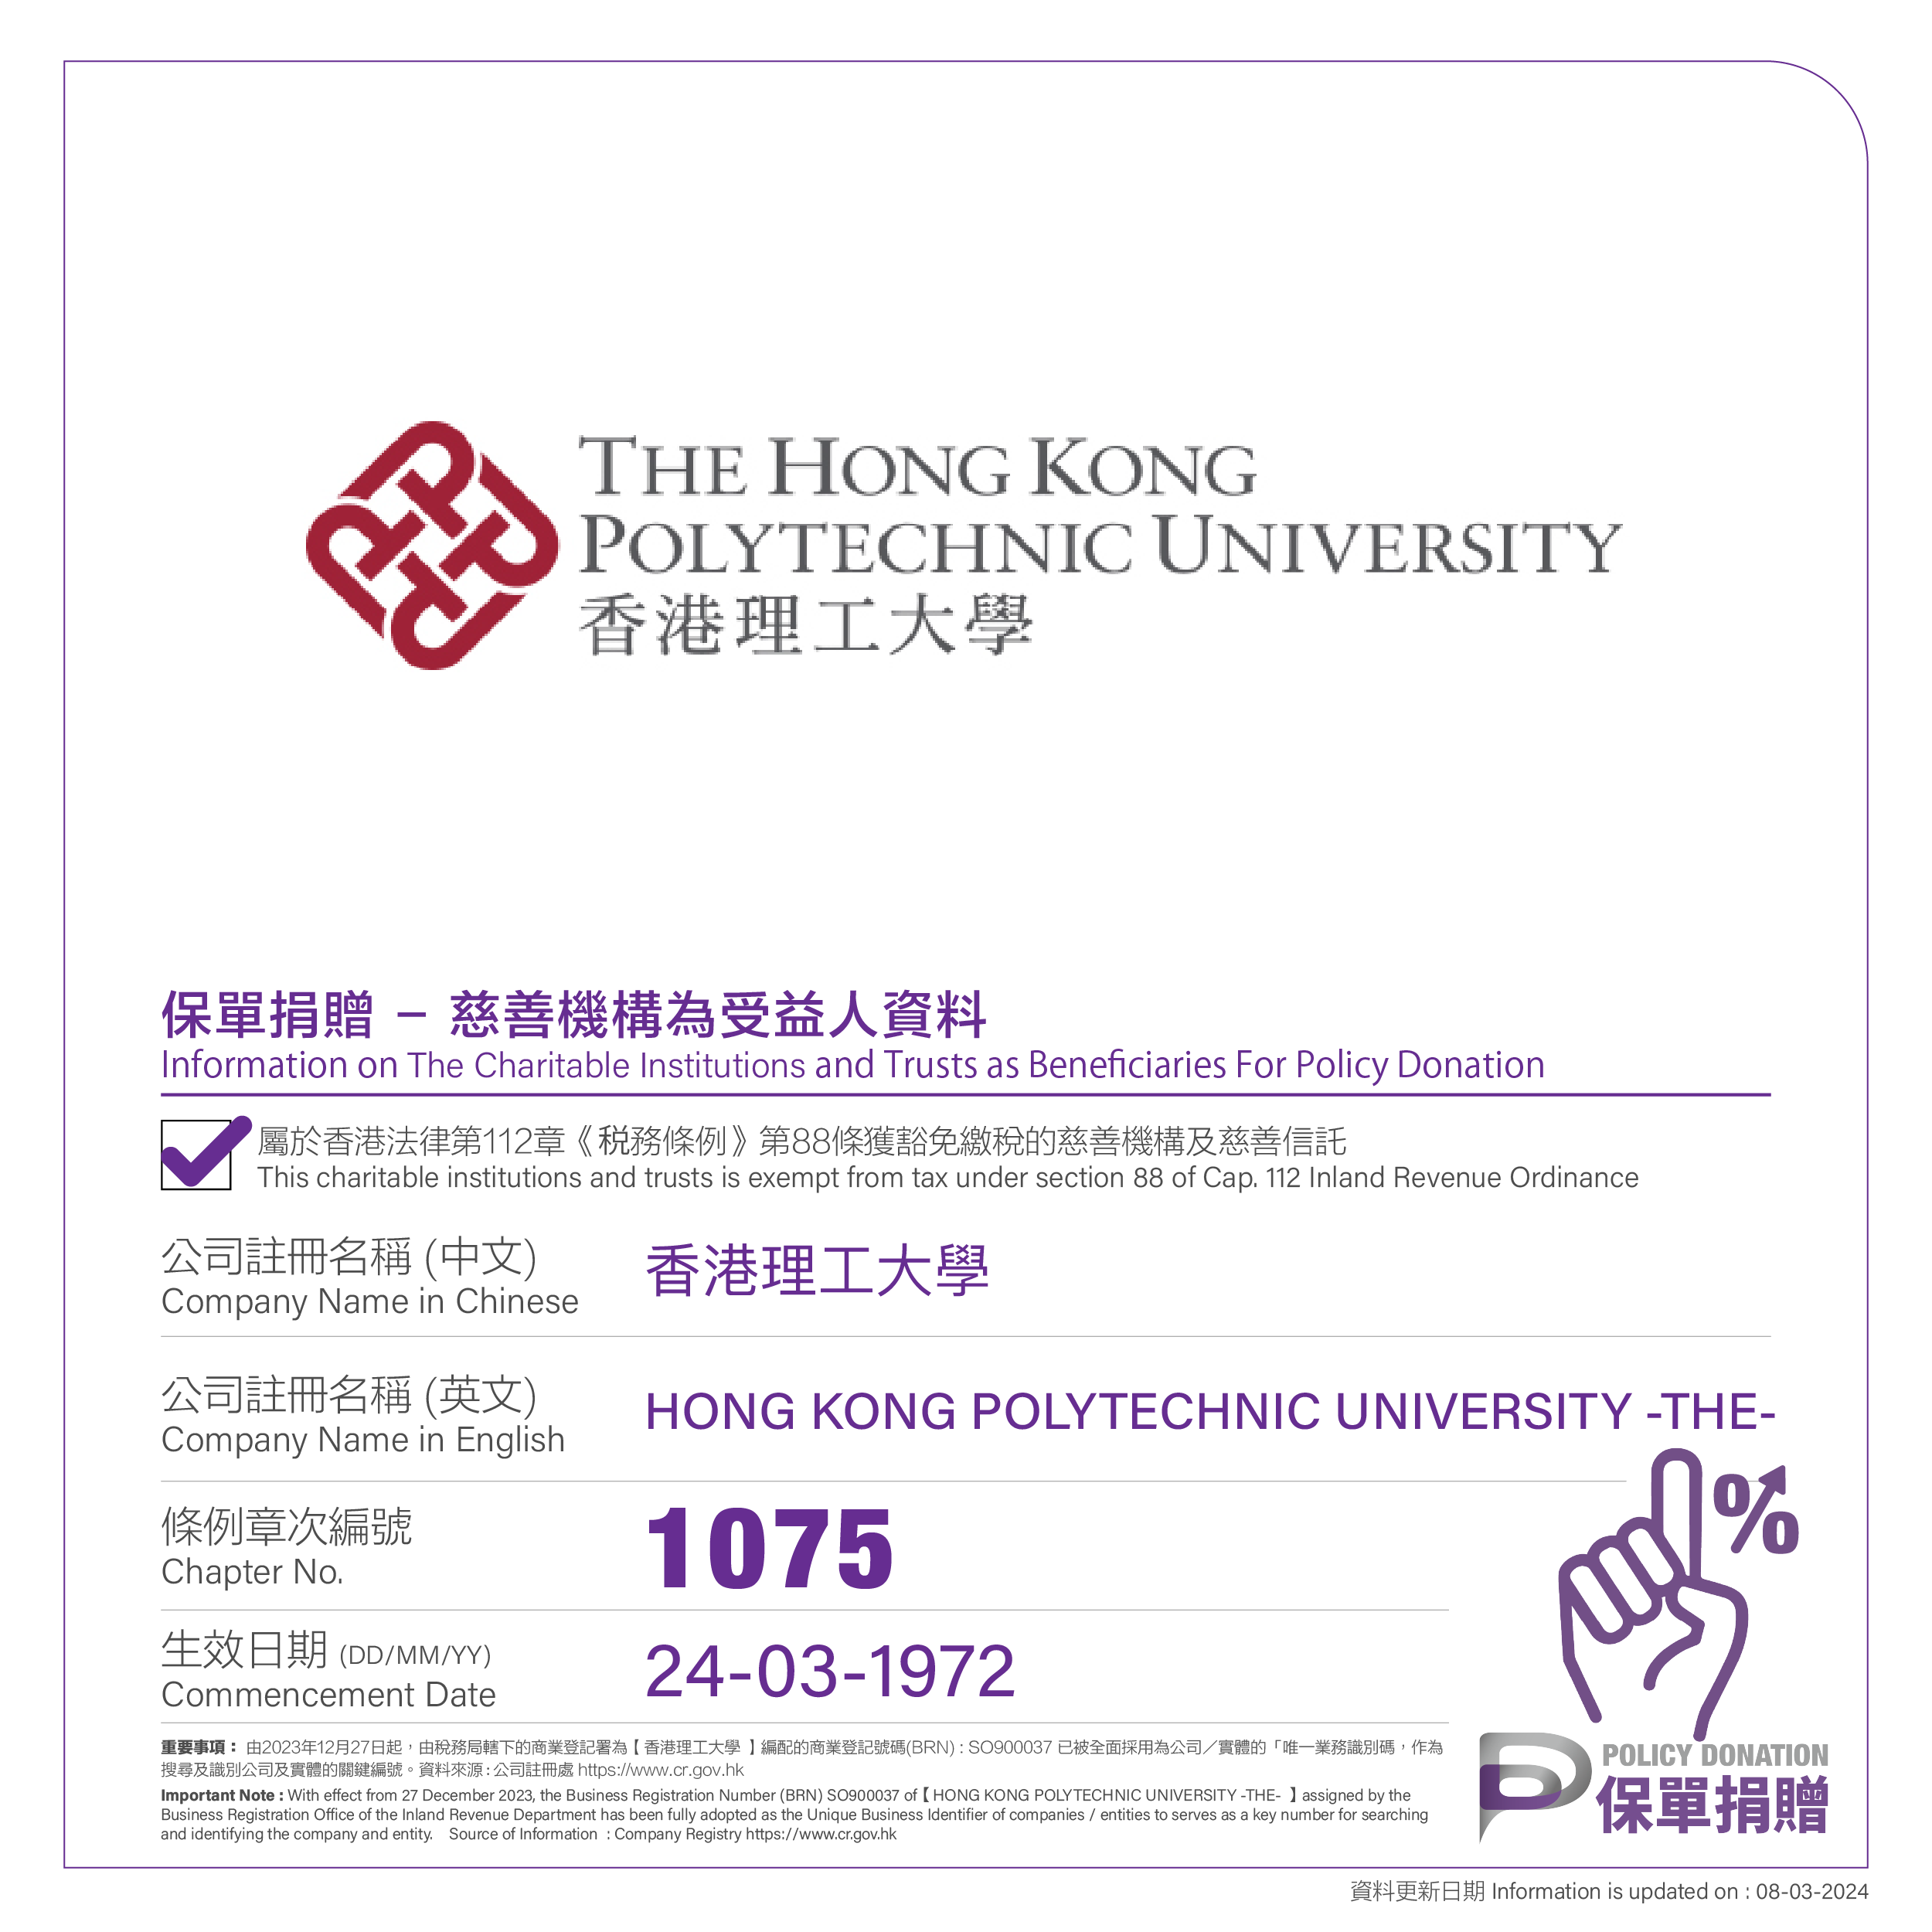
HONG KONG POLYTECHNIC UNIVERSITY ORDINANCE, -THE-